🏡 Mortgage Application - Document Needed
Buying a home is exciting, but getting your mortgage approved can feel overwhelming if you are not prepared. One of the easiest ways to make the loan process smoother is to have your financial documents ready before you apply.
While documentation requirements vary depending on the loan program and your financial situation, below are some of the most commonly requested documents.
🪪 1. Identification Documents
Your lender will need to verify your identity and residency status.
Common documents include:
- Driver’s license or government-issued photo ID
- Social Security number
- Permanent Resident Card or applicable visa documentation, if required
💼 2. Employment & Income Documents
For salaried or W-2 employees, lenders typically request:
- Most recent 30 days of pay stubs
- W-2 forms for the past 2 years
- Employment history for the past 2 years
If you recently changed jobs, your lender may also request an employment offer letter or additional employment verification.
🏦 3. Bank & Asset Statements
Lenders verify that you have sufficient funds for the down payment, closing costs, and any required reserves.
Be prepared to provide:
- Most recent 2 months of checking and savings account statements
- Investment or brokerage account statements
- Retirement account statements, if those funds will be used for the transaction
💡 Important Tip
Large or unusual deposits may need to be documented. Avoid moving large amounts of money between accounts unnecessarily while your mortgage is being processed.
💰 4. Down Payment Documentation
Your lender will need to determine where your down payment and closing funds are coming from.
Acceptable sources may include:
- Checking or savings accounts
- Investment accounts
- Retirement funds
- Proceeds from the sale of another property
- Gift funds from an eligible donor
- Other acceptable sources depending on the loan program
If gift funds are being used, additional documentation such as a gift letter may be required.
🏠 5. Current Housing Information
You may be asked to provide information about your current residence, including:
- Current address
- Previous addresses covering approximately 2 years
- Current mortgage statement, if you own your home
- Property tax information
- Homeowners insurance information
- Landlord information or rental history, when required
📋 6. Existing Debt Information
Your credit report will normally identify most of your existing obligations, but additional documentation may sometimes be required for:
- Student loans
- Auto loans
- Personal loans
- Credit cards
- Child support or alimony obligations
- Other mortgages
If you recently paid off a debt, your lender may request documentation showing the updated or zero balance.
🏘️ 7. Documents for Other Real Estate You Own
If you own additional properties, your lender may request:
- Current mortgage statements
- Property tax bills
- Homeowners insurance information
- HOA statements
- Current lease agreements for rental properties
If rental income is being used to qualify for the mortgage, additional tax or income documentation may also be required.
📝 8. Property Documents
Once you are under contract to purchase a home, the lender will typically need:
- Signed purchase agreement
- Property address
- Earnest money documentation
- Homeowners insurance information before closing
Your real estate agent, lender, and closing attorney will coordinate many of these documents throughout the transaction.
💼 Self-Employed Borrowers
If you are self-employed, own a business, work as an independent contractor, or receive a significant portion of your income through a business, the documentation requirements may be different from those of a traditional W-2 employee.
Lenders may request:
- Personal federal tax returns for the past 2 years
- Business tax returns for the past 2 years, when applicable
- Year-to-date Profit & Loss Statement
- Business balance sheet, when required
- Business bank statements
- Verification of business ownership
- Business license, when applicable
- CPA or accountant documentation in certain situations
The lender will generally review the stability and history of the business as well as the income available to you personally.
🏦 Alternative Loan Programs
Traditional tax-return qualification is not the only option for every self-employed borrower.
Depending on your situation, alternative financing programs may be available, including:
- Bank statement loans
- 12-month or 24-month bank statement programs
- Profit & Loss statement programs
- Asset-based qualification programs
- DSCR loans for investment properties
These programs have different qualification standards, down payment requirements, rates, and documentation requirements.
If you are self-employed, speaking with a loan officer before beginning your home search can help determine which financing option best fits your income structure.
🔍 Additional Documents May Be Required
Every borrower and every loan is different. Depending on your situation, additional documents may be requested for:
- Bonus income
- Commission income
- Overtime income
- Rental income
- Retirement income
- Social Security income
- Gift funds
- Divorce or separation agreements
- Bankruptcy history
- Previous foreclosure
- Recent employment changes
- Immigration or residency documentation
Do not be concerned if your lender asks for additional paperwork during underwriting. Mortgage approval is a documentation-driven process, and follow-up requests are common.
✅ Before You Apply: Mortgage Preparation Checklist
To help your mortgage process move smoothly:
✓ Gather your income and asset documents early
✓ Avoid opening new credit accounts
✓ Avoid making large purchases before closing
✓ Avoid depositing large amounts of cash
✓ Keep records of any large deposits or transfers
✓ Keep your employment and income situation stable when possible
✓ Respond quickly to lender documentation requests
✓ Check with your loan officer before making major financial changes
💡 Pro Tip: Get Pre-Approved First
Getting pre-approved before you seriously start shopping for a home can help you understand:
- How much home you may qualify for
- Your estimated monthly payment
- Your down payment options
- Available mortgage programs
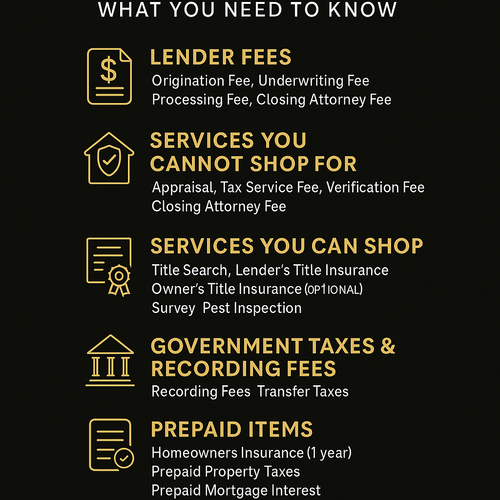
- Potential closing costs
- Whether any financial issues should be addressed before making an offer
A strong pre-approval can also put you in a better position when you find the right home.
🏡 Ready to Start Your Home-Buying Journey?
Whether you are a first-time home buyer, move-up buyer, self-employed borrower, or real estate investor, understanding your financing options before you start shopping can make the entire process easier.
Contact me to discuss your home-buying goals, mortgage options, and pre-approval.
Pradeep Sivagurunathan
Real Estate Agent & Mortgage Loan Officer
NMLS #2542840
Loan programs, documentation requirements, interest rates, down payment requirements, and qualification guidelines vary by lender, loan program, property type, and borrower circumstances. This information is provided for general educational purposes and does not constitute a commitment to lend.
Check out this article next